FINANCIAL REPORTING
Equipment Appraisal for Financial Reporting
Equipment appraisal services for financial reporting covering fair value measurement, purchase price allocation, and impairment testing, prepared in accordance with USPAP. Ironclad Desktop Valuations appraises manufacturing, construction, IT, and medical equipment for GAAP financial statements and audit support nationwide.
- Fair Value Measurement (ASC 820)
- Audit-Ready USPAP Reports
- Nationwide Coverage, No On-Site Visit
EQUIPMENT COVERAGE
From CNC Production Lines to Diagnostic Imaging Systems, Here's the Equipment We Value for Financial Statements
Manufacturing & Industrial Machinery
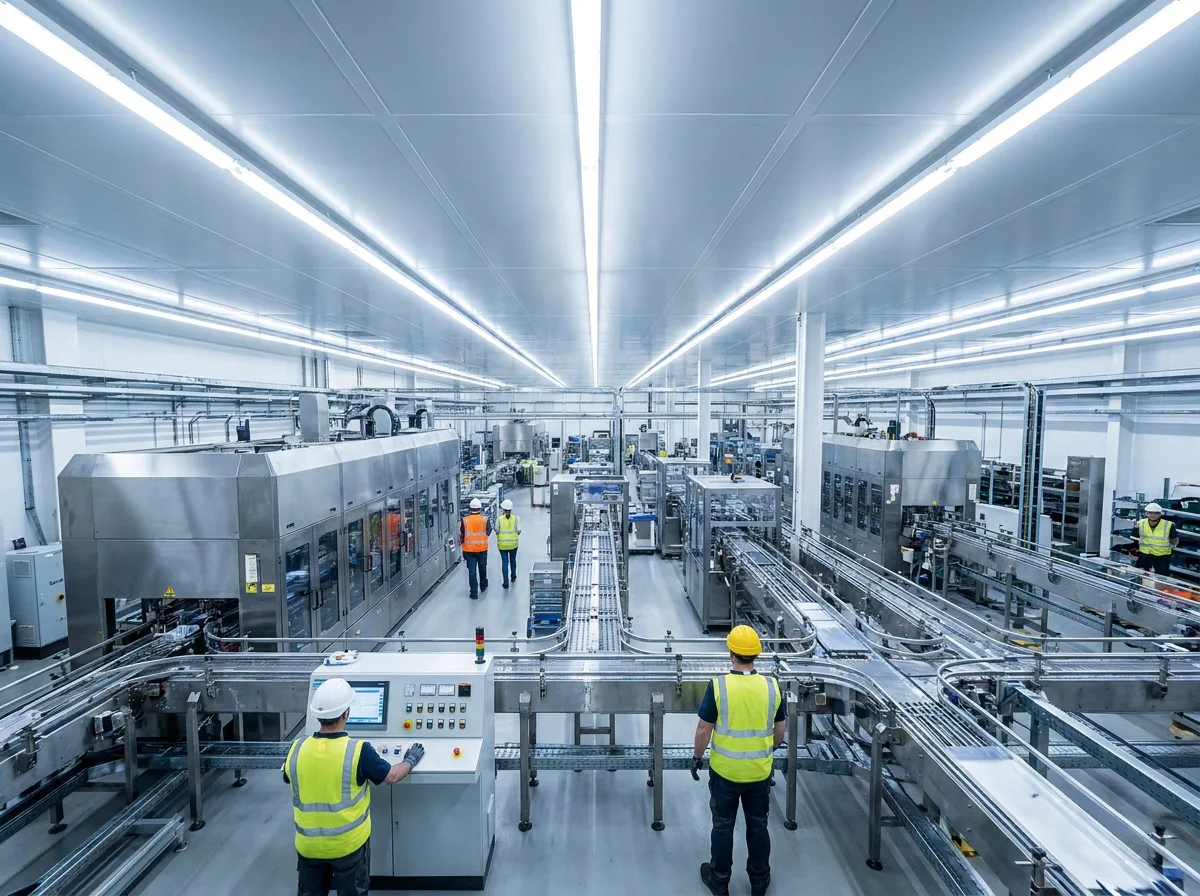
CNC machines, production lines, and plant machinery valued at fair value for balance-sheet reporting and audit support.
Construction & Heavy Equipment
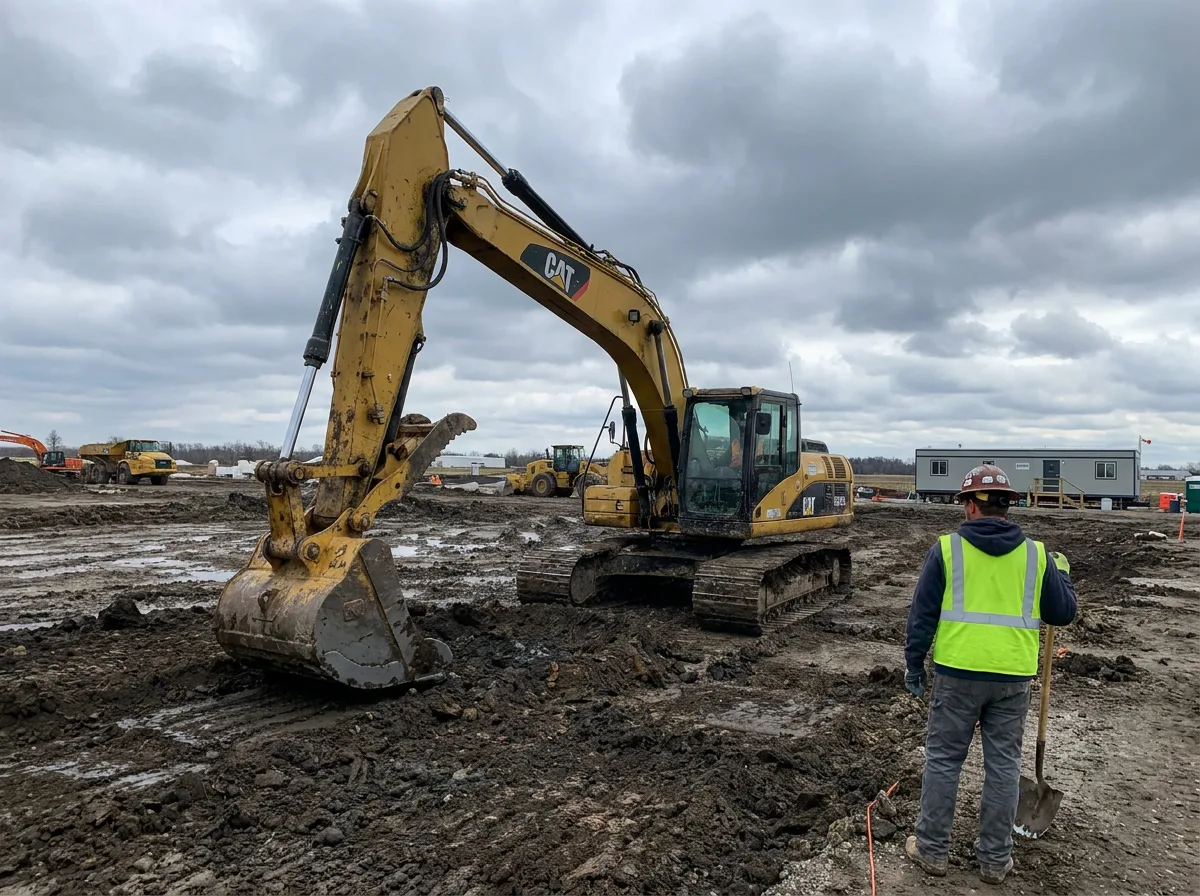
Excavators, loaders, and dozers appraised for fixed-asset schedules, impairment testing, and fresh-start accounting.
IT & Office Equipment
Servers, workstations, and networking infrastructure valued for GAAP financial statements and technology-asset reporting.
Medical & Laboratory Equipment
Diagnostic, imaging, and lab equipment appraised at fair value for practice financial statements and audits.
Transportation & Fleet Equipment
Trucks, trailers, and titled fleet assets valued for depreciation schedules and financial reporting.
Farm & Agricultural Equipment
Tractors, implements, and agricultural machinery appraised for farm balance sheets and lender financial reporting.
FINANCIAL REPORTING STANDARDS
Fair Value Under ASC 820 Anchors Equipment on the Balance Sheet
Financial reporting values equipment on a fair value basis, the price the assets would sell for in an orderly transaction between market participants. ASC 820, Fair Value Measurement, defines that standard and the hierarchy of market inputs behind it, and a supported appraisal documents the evidence so the number holds up with your auditors.
Several reporting events call for an independent machinery and equipment appraisal. Under ASC 805, Business Combinations, an acquirer records acquired equipment at fair value on the opening balance sheet as part of purchase price allocation. Under ASC 360, a triggering event may require impairment testing, where the carrying value of long-lived assets is measured against their fair market value. Fresh-start reporting after reorganization restates assets at fair value as well.
Each report is prepared in accordance with USPAP and documents condition, age, remaining useful life, and comparable market data behind every conclusion, so your finance team and external auditors have a defensible basis for the recorded value. Where a lender is also involved, we can report loan collateral value in the same engagement. Tell us your reporting or audit deadline, and we confirm the timeline up front. See our equipment appraisal pricing for financial reporting engagements.
HOW IT WORKS
What Happens Between Your Request and Your Fair Value Report
- 01
Share Your Fixed-Asset Records
Send your equipment list, specifications, model and serial numbers, and acquisition dates for the assets going on the balance sheet.
- 02
Market-Based Value Conclusion
We research comparable sales and current market data to conclude fair value or fair market value, whichever standard your reporting event requires.
- 03
Documentation Your Auditors Can Rely On
You receive a USPAP-compliant report with the market evidence behind each conclusion, formatted for your finance team and external auditors.
STANDARDS & CREDENTIALS
The Credentials Behind Every Fair Value Conclusion
Fair value conclusions carry real audit exposure if the underlying analysis can't be defended, so every report we prepare follows USPAP from research through delivery. Our appraisers hold credentials with organizations including the American Society of Appraisers (ASA) and the NEBB Institute (CMEA), giving your controller and external auditors a valuation they can stand behind at close.
ASA Accredited
CMEA
CAGA
USPAP
FAQ
Financial Reporting Appraisal Questions
What value standard is used to appraise equipment for financial reporting?
Financial reporting uses fair value, defined by ASC 820 as the price the equipment would sell for in an orderly transaction between market participants at the measurement date. We identify the appropriate premise for your reporting event and document the market inputs behind it in a USPAP-compliant report your auditors can rely on.
What is the difference between fair value and fair market value?
Fair value is an accounting standard defined under ASC 820 for financial reporting and centers on market participant assumptions. Fair market value is the standard used for tax and many transactional purposes, reflecting a willing buyer and willing seller. The conclusions are often close, but the definitions differ, so we confirm which standard your engagement requires before we begin.
Do auditors require an independent equipment appraisal?
External auditors frequently expect independent support for equipment carried at fair value, particularly after an acquisition, an impairment event, or a reorganization. An independent, USPAP-compliant appraisal gives the auditor documented market evidence for the recorded value rather than book estimates, which streamlines the audit and supports the financial statements.
When should equipment be revalued for impairment testing?
Under ASC 360, long-lived assets are tested for impairment when a triggering event suggests their carrying value may not be recoverable, such as a significant decline in market conditions, physical damage, or a change in how the equipment is used. An appraisal establishes the current fair market value to compare against the carrying amount so any write-down is supported.
Can a desktop appraisal be used for financial reporting and audit support?
Yes. USPAP standards govern how an appraisal is developed and reported, not how the equipment is inspected. Our desktop methodology applies the same market analysis and documentation used in an on-site inspection, producing an audit-ready valuation without the cost and delay of a site visit. Confirm any specific inspection requirement with your auditor first.
GET STARTED
Request a Fair Value Equipment Appraisal
Tell us what's on your fixed-asset register and your reporting or audit deadline, and we'll confirm scope and timing before work begins.